SBI & HDFC MF Move Into Tenneco Clean Air India.
What are these Institutions Seeing?
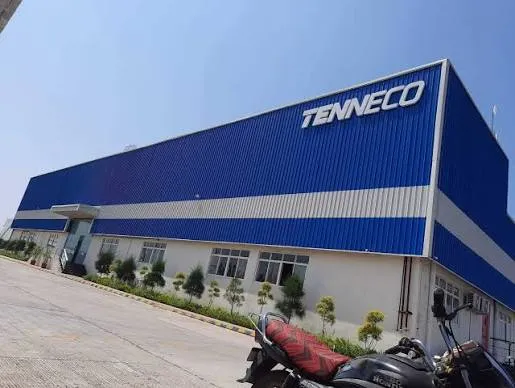
Tenneco Clean Air India recently attracted significant institutional buying after its promoters sold around 15% of the company at approximately ₹525 per share.
The transaction saw SBI Mutual Fund build a sizeable ~6.1% position, while HDFC Mutual Fund acquired around 0.5%. The broader institutional participation suggests that the promoter sell-down was absorbed by investors willing to take a long-term view of the business.
But the interesting question is not simply who bought. It is why institutions were willing to buy a large stake at this stage of Tenneco’s growth journey.
Smart Money Express View: Following the Capital Trail
Tenneco is much more than a conventional auto-ancillary company.
It is a technology-led Tier-1 supplier of emission-control systems, engine components and advanced suspension systems, with long-standing relationships with major automotive OEMs.
The strongest part of the investment thesis is its ₹12,400 crore lifetime order book as of March 2026—more than twice its FY25 revenue. The order book provides substantial visibility for future growth and reflects programmes already awarded by OEM customers.
Tenneco also holds leading positions across several categories, including passenger-vehicle suspension, engine bearings, commercial-vehicle clean-air systems and off-highway clean-air solutions.
The company is increasingly benefiting from a structural shift towards higher technology and higher content per vehicle, rather than simply relying on growth in vehicle volumes.
The Growth Engines
1. ₹12,400 Crore Order Book
The order book provides unusual revenue visibility and supports management’s expectation of a sustained double-digit growth trajectory.
2. Premiumisation
Advanced Ride Technologies—including sophisticated suspension systems—are gaining importance as Indian consumers move towards SUVs and premium vehicles. This increases component value per vehicle.
3. Export Opportunity
India currently contributes the overwhelming majority of Tenneco’s revenue, but the company is positioning India as a competitive global manufacturing and export base.
4. Capacity Expansion
Tenneco has announced around ₹140 crore of greenfield capex for new Clean Air and Advanced Ride Technologies facilities to support future OEM programmes.
5. Acquisition Optionality
Management has indicated that its debt-free balance sheet and cash generation could support acquisitions in adjacent automotive technologies.
Fundamental Snapshot
FY26 was a strong year:
FY25
FY26
Revenue
₹4,890 cr
₹5,404 cr
EBITDA
₹815 cr
₹926 cr
PAT
₹553 cr
₹604 cr
ROCE
57%
94%
ROE
43%
43%
The standout number is 94% ROCE.
Combined with zero net debt, negative working-capital days and strong cash generation, this indicates an exceptionally capital-efficient manufacturing business.
However, Q1 FY27 provides an important caution. Revenue grew around 20%, but EBITDA grew only about 8% and PAT declined marginally. The key issue to monitor is therefore whether strong revenue growth translates into sustained margin and earnings expansion.
Technical Picture
The technical picture currently contrasts with the fundamental story.
At around ₹515–520, the stock was trading below its 20, 50, 100 and 200-day moving averages, with RSI around 39 and MACD negative.
In simple terms:
Fundamentals: Strong
Order visibility: Exceptional
Technical momentum: Weak
For smart-money followers, this divergence is worth watching. The stock’s correction has brought the price well below its recent highs, while the underlying order book and business strategy remain intact.
Smart Money Express Take
Tenneco Clean Air India presents an interesting example of institutional money buying into future earnings visibility rather than simply chasing current momentum.
The investment thesis can be summarised in five words:
Leadership + Technology + Orders + ROCE + Optionality
The ₹12,400 crore order book, market-leading positions, premiumisation opportunity, export potential and extraordinary 94% ROCE make Tenneco an unusual auto-component story.
The key risk is valuation and execution. At roughly 35x FY26 earnings, the market is already assigning a premium to the company’s quality and future growth.
The next few quarters will therefore be crucial.
Can Tenneco convert its massive order book into revenue, protect margins and maintain its exceptional capital efficiency?
That is the capital trail Smart Money Express will be watching.
Smart Money Express tracks smart-money flows, business developments and market signals for informational purposes. This article is not a buy or sell recommendation.
Smart Money Express publishes financial journalism, not investment advice. Nothing here is a recommendation to buy or sell any security. Flow indicators describe observed institutional activity over a stated period; they are not ratings and carry no view on future prices. Do your own research or speak to a registered adviser.
More from Capital Flow – India
Analysis Catamaran Ventures Adds Kirloskar Oil Engines and Ador Welding to Its Portfolio
1 Oct 2026
Analysis Ashish Kacholia Places a ₹20 Crore Bet on Asian Energy Services.
Is Smart Money Positioning for India's Energy Capex Cycle?
23 Sept 2026
Analysis Why Thangamayil Jewellery Is Attracting Insider Confidence
Promoters and promoter group entities of Thangamayil Jewellery Limited have actively increased their stake in the company through open-market purchases
20 Sept 2026
Comments
No comments on this piece yet. Yours would be the first.
Leave a comment
Comments are read before they appear. Your email address is never published.
Please keep it civil and on the subject of the article. We remove anything defamatory, and we cannot answer questions about what to buy or sell.